

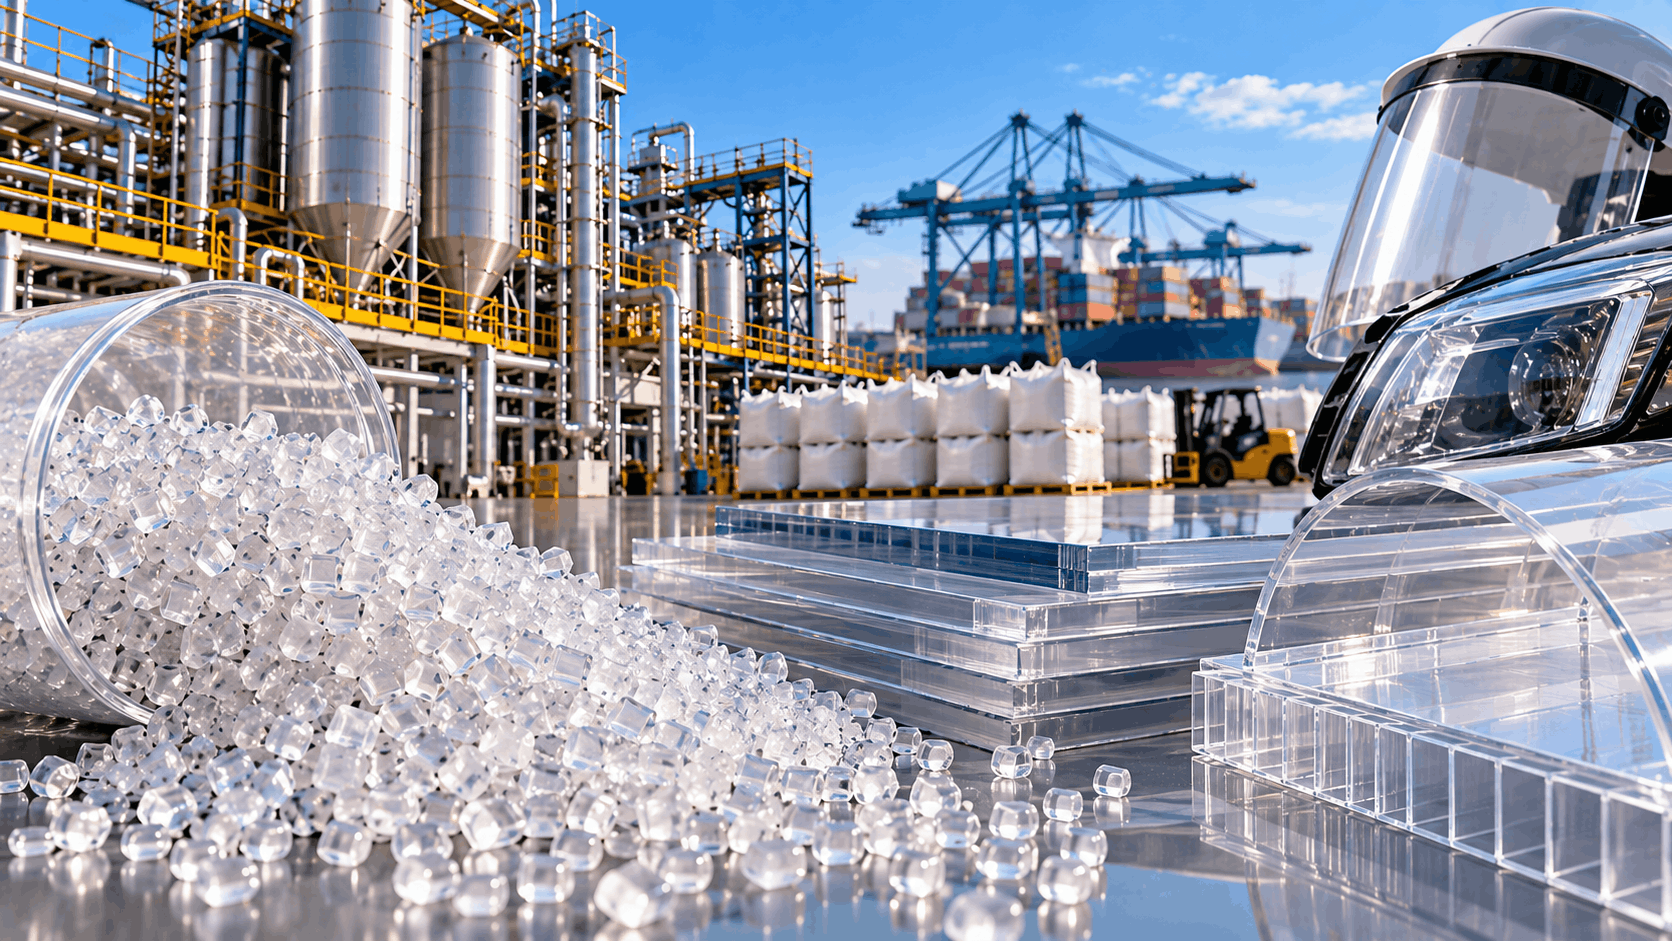
Polycarbonate Price Trend Q3 2026: China & US Update
Polycarbonate price trend watchers have a fresh data point to work with heading into Q3 2026. China’s ex-works price sits at USD 2,110.32 per metric ton as of August 2026. The US figure, quoted CIF, comes in at USD 2,266.00 per metric ton over the same period. That’s a meaningful spread, and it’s not purely coincidence.
Polycarbonate shows up everywhere once you start looking. Automotive headlamp lenses, eyewear, electronics housings, construction glazing. A shift in its price doesn’t stay contained to one industry for long. It moves through supply chains and shows up in finished goods a few months later.
Current Polycarbonate Prices: China vs USAPolycarbonateChinaEXWUSD 2,110.32/MTAugust 2026PolycarbonateUSACIFUSD 2,266.00/MTAugust 2026That’s a USD 155.68 difference per metric ton. Not small. And the gap isn’t just about raw production cost, either.
Context matters here:
China’s number is EXW, meaning it reflects factory gate price before freight or any handling gets added on.The US figure is CIF, so freight and insurance are already baked into that number.Both are snapshots from August 2026, so monthly volatility can shift either figure within a few weeks.Comparing an EXW number to a CIF number head on isn’t quite fair. Freight alone can add a few hundred dollars per ton depending on the route and fuel costs at the time of shipping. So part of that USD 155.68 gap is simply the incoterm basis doing its job.
What’s Behind the Polycarbonate Price TrendA few forces tend to pull polycarbonate pricing in different directions at the same time.
Bisphenol A and phosgene remain the core feedstocks for polycarbonate production. When crude derivatives swing, producers feel it fast. Margins in this segment aren’t generous enough to absorb much cost pressure without passing it downstream.
China runs enormous domestic polycarbonate capacity, tied closely to its electronics and automotive manufacturing base. That scale gives Chinese producers pricing leverage that exporters in other regions often can’t match. The US, by comparison, relies more heavily on imports to meet certain grades of polycarbonate demand, which adds cost layers that domestic production in China simply skips.
Freight costs deserve their own mention too. Trans-Pacific shipping rates, container availability, and port delays all land somewhere in that CIF figure. A single disruption at a major port can shift the US number meaningfully within a month, even when nothing changed on the production side.
Currency plays a role as well. Polycarbonate trades globally in dollars. When the yuan strengthens or weakens against the dollar, it changes what Chinese exporters are effectively willing to sell at, even if the headline dollar price looks steady.
Q3 2026 Outlook for Buyers and InvestorsSourcing teams reading this probably want a straight answer. Here’s a reasonable one.
China’s lower EXW price looks appealing for buyers who can manage their own logistics and don’t mind the added coordination. But factory gate pricing hides real costs. Freight, customs clearance, lead time risk. Add those in and the comparison with US landed cost gets closer than the headline numbers suggest.
Investors tracking engineering plastics might find the US side more interesting right now. A higher landed cost, driven partly by import reliance, often points toward room for expanded domestic capacity. A few US producers have signaled interest in exactly that kind of expansion over the past year.
Anyone advising clients in automotive components, eyewear manufacturing, or electronics enclosures should treat this spread as more than background noise. Polycarbonate costs tend to show up in finished product pricing with a lag of roughly one to three months. Watching this trend now gives procurement teams a head start on budgeting.
Should buyers expect the gap to close anytime soon? Probably not in the near term. The structural differences between the two markets, domestic capacity in China versus import dependence in the US, aren’t going away overnight. Feedstock cost trends and shipping conditions will likely matter more than anything else in determining whether the spread widens or narrows through the rest of Q3.
One more thing worth flagging: locking contracts based on outdated pricing is a real risk in a market that moves this fast. August 2026 numbers are useful as a reference point. Treating them as fixed for the quarter ahead would be a mistake.
ConclusionThe polycarbonate price trend ↗ for Q3 2026 shows China at USD 2,110.32/MT EXW and the USA at USD 2,266.00/MT CIF, both as of August 2026. That USD 155.68 gap reflects real differences in production scale, freight structure, and import dependence, not random market noise. For procurement teams, investors, and advisers tracking engineering plastics costs, this is data worth checking regularly rather than treating as a one-time reference.
FAQ SectionWhat is the current polycarbonate price trend in China and the USA?
As of August 2026, China’s polycarbonate price is USD 2,110.32/MT EXW, while the USA sits at USD 2,266.00/MT CIF. The gap reflects differences in incoterm basis, freight costs, and how much each market depends on imported versus domestically produced polycarbonate.
Why is polycarbonate cheaper in China than in the USA?
China’s EXW price excludes freight and insurance, unlike the CIF figure quoted for the USA. China also has massive domestic production capacity tied to its electronics and automotive sectors, which gives producers more pricing control than importers elsewhere typically have.
What factors drive polycarbonate prices the most?
Feedstock costs, mainly bisphenol A and phosgene, account for most of the movement. Freight rates, port conditions, and currency shifts add further pressure. Polycarbonate runs on thin margins, so cost changes upstream tend to reach buyers within weeks rather than months.
How frequently do polycarbonate prices change?
Prices can shift monthly or even faster depending on feedstock volatility and shipping disruptions. The August 2026 figures here serve as a solid benchmark, but buyers finalizing contracts should always pull more recent pricing before committing to terms.
What’s the outlook for polycarbonate prices in Q3 2026?
The China-USA spread is likely to persist through Q3 2026, driven by structural differences in production capacity and import reliance. Whether it widens or narrows will largely depend on feedstock cost trends and how shipping conditions develop over the quarter.